The 100-Year Hand-Off: The Chicago Bears, Indiana, and the Brewing Tax Battle
A Century of Tradition Meets Modern Fiscal Reality
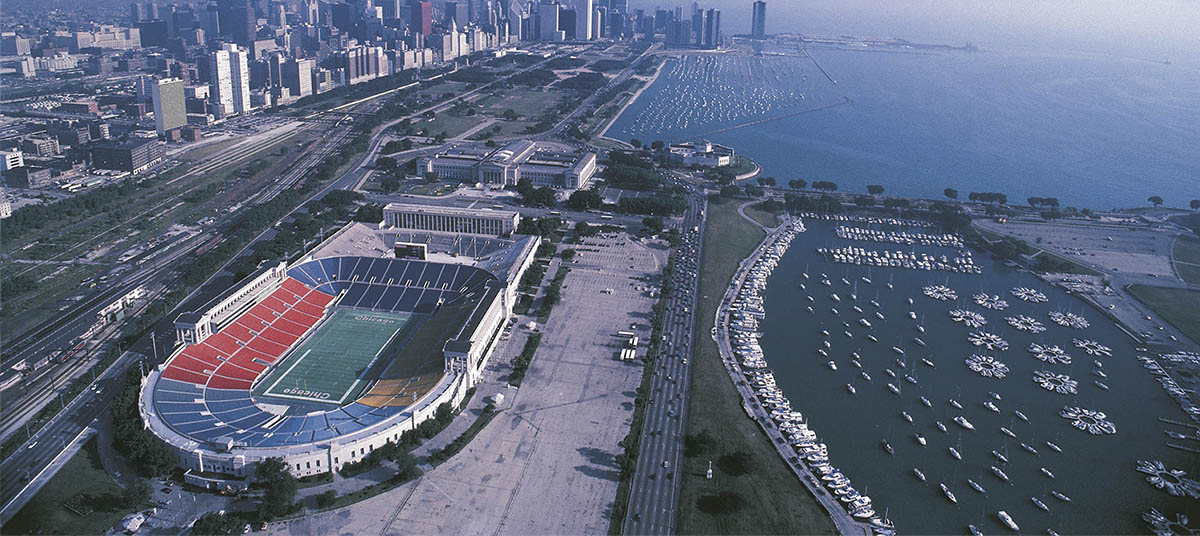
For more than a century, the Chicago Bears have been the heartbeat of football in Illinois. Established in 1920, the franchise is woven into the very fabric of Chicago’s cultural and civic identity. For generations, the lakefront has been the site of triumphs, heartbreaks, and a steady stream of tax revenue for the city and state. However, that century-long legacy is currently facing its most significant challenge as the team explores options that could lead them away from the Windy City.
Today, the discussion has shifted from the playbook on the field to the ledger in the boardroom. As negotiations with Illinois officials remain in a state of flux, a new and serious possibility has surfaced: a relocation to Hammond, Indiana. This isn't merely a change in zip code; it represents a seismic shift in tax jurisdiction, infrastructure responsibility, and the potential allocation of hundreds of millions in public funds.
This is no longer a localized debate about suburban development. We are witnessing an interstate fiscal chess match. If Indiana moves forward with aggressive tax incentives, property tax abatements, or creative public financing to lure the Bears across the border, the ripple effects will be felt by every resident in the region. It raises a fundamental question for northwest Indiana and Illinois taxpayers alike: at what point does the public cost of a private stadium become too high?
The Indiana Proposal: Millions in Potential Tax Increases
In the early months of 2026, the Indiana General Assembly’s Legislative Services Agency provided a sobering look at the numbers. They released a fiscal impact statement regarding a pending stadium financing bill. While the bill was initially linked to facilities in Indianapolis, its framework serves as the likely blueprint for any deal involving Hammond and the Bears.
The analysis from state analysts was clear: the project could trigger tens of millions of dollars in tax increases over the coming years. These funds would be necessary to cover the massive debt service and the specialized infrastructure required for a modern NFL venue. Under the proposed Indiana legislation, several tax mechanisms could be deployed:
- New Local Option Taxes: Local governments could be authorized to implement or increase taxes specifically to fund transportation, utilities, and safety infrastructure surrounding the stadium.
- Redirected Revenue Streams: Existing tax revenues that currently support schools or public works could be diverted to ensure the project’s financial solvency.
- Long-Term Cumulative Impact: Over a multi-decade bond cycle, the total burden on property owners and small businesses in the surrounding area could reach staggering figures.
Indiana officials have noted that stadium financing packages almost always rely on a complex cocktail of sales tax increments, local option income taxes, and property tax levies. For the average resident of northwest Indiana, this isn’t an abstract policy debate; it is a direct line to their future tax bills.
The Multi-State Tug-of-War: Who Ultimately Pays?
While Indiana evaluates its financing mechanics, the long-running saga of the Chicago Bears’ proposed stadium in Arlington Heights continues to simmer. This dual-track negotiation has created a unique scenario where two neighboring states are effectively competing to see who can offer the most favorable tax environment for a multi-billion dollar franchise. This competition frequently places taxpayers in a precarious position.
As reported by Advantage News, both Illinois and Indiana face substantial taxpayer risks if they approve incentive packages tied to a relocation. These costs are rarely transparent and often include:
- Tax Increment Financing (TIF) Districts: These districts capture all future increases in property tax revenue to pay for stadium costs, effectively starving local schools and parks of that growth for 23 years or more.
- Infrastructure Reimbursements: Taxpayers often end up footing the bill for road expansions, sewage upgrades, and electrical grid improvements that benefit the stadium owner.
- Sales Tax Rebates: A portion of every jersey or hot dog sold might go back to the team owners rather than into the public treasury.
- Valuation Adjustments: Battles over property tax assessments can lead to significantly lower tax payments from the team, shifting the burden onto other local property owners.
The competitive nature of professional sports means that lawmakers are often under immense pressure to ‘win’ the franchise, sometimes at the expense of a clear-eyed economic benefit analysis for their constituents.
Rising Opposition in the Illinois House and Local Municipalities
In Illinois, the pushback has become more vocal as the reality of the tax implications sets in. According to reporting from the Chicago Sun-Times, the resistance is building on several fronts:
- Legislative Skepticism: Members of the Illinois House have expressed deep concerns regarding property tax incentives specifically tailored for a new stadium. There is a growing sentiment that public money should not be used to enrich a private organization that already has high profitability.
- Local Government Alarm: Officials in Arlington Heights and neighboring suburbs are questioning how the public financing burden will affect homeowners and small business owners who are already struggling with high property taxes.
- Revenue Erosion: Critics point out that every dollar granted as a tax abatement or exemption is a dollar that doesn't go toward funding police, fire departments, or public education.
The Sun-Times analysis underscores a critical point for taxpayers: while proponents often talk about ‘job creation’ and ‘economic revitalization,’ the underlying fiscal mechanics are zero-sum. Incentives cost money, and that revenue shortfall must be covered by someone else.
Decoding the Mechanics: How Stadium Financing Affects You
As a tax professional, I often see clients surprised by how localized stadium deals can affect their personal bottom line. These deals involve significant trade-offs that are not always apparent on the surface. When a stadium project enters the public discourse, several common tools are typically proposed, each with its own tax impact:
Sales Tax Increments
Local jurisdictions may decide to divert future sales tax revenue generated at the stadium site to pay off construction bonds. While this sounds like the project is ‘paying for itself,’ it actually removes money from the general fund that would have otherwise supported broader community services.
Property Tax Abatements and TIFs
By freezing property tax values for the developer, the city or county limits its own revenue growth. If the cost of providing services to the new stadium area (like police and traffic control) exceeds the frozen tax revenue, other property owners must make up the difference through higher rates.
Local Option Income and Excise Taxes
You may see proposals for new ‘hotel taxes,’ ‘food and beverage taxes,’ or even a small bump in local income taxes. These are designed to target visitors, but they often end up affecting local residents who patronize nearby businesses or who live within the taxing district.
What Every Taxpayer Should Watch For
If your community in Illinois or Indiana is currently navigating a stadium proposal, you must look beyond the team colors and stadium renderings. As a resident and taxpayer, clarity is your best defense. Consider the following:
- Examine the Revenue Streams: Are the funds coming from new taxes, or are existing revenues being diverted away from essential services?
- Evaluate the Debt Maturity: Check the payback period on the bonds. Long-term debt means that your children and grandchildren could still be paying for a stadium that might be considered obsolete in 30 years.
- Scrutinize Job Claims: Are the projected jobs full-time with benefits, or are they largely seasonal, low-wage positions? Most independent economists find that stadium ROI is lower than proponents claim.
- The Opportunity Cost: Ask yourself what else that money could buy. Could those millions in incentives be better used for regional infrastructure, tax relief for small businesses, or improved education?
Public scrutiny is essential because once these tax structures and bond agreements are signed, they are nearly impossible to reverse. Whether the Bears stay in Chicago, move to Arlington Heights, or cross the border into Indiana, the decision is about much more than football loyalty. It is a fundamental question of public finance policy and who bears the risk of private enterprise.
Taxpayers deserve a seat at the table to understand exactly how much they will pay, how it will be collected, and what the true return on investment will be. If you are concerned about how local tax changes or new state legislation might affect your business or personal property taxes, now is the time to stay informed. Explore our tax planning services to see how we can help you navigate the changing fiscal landscape in your area. Schedule a consultation today to ensure your financial plan is prepared for whatever happens next on the lakefront or across the border.
Beyond the immediate bond debt, there is the often-overlooked issue of the 'Circuit Breaker' in Indiana’s property tax code. For those unfamiliar with the Hoosier State’s tax structure, Indiana has a constitutional cap on property taxes—limiting them to 1% of gross assessed value for homesteads, 2% for rental properties and farmland, and 3% for all other real property. When a massive project like an NFL stadium is proposed, the financing often requires 'referendum debt' or specialized taxing districts that can operate outside of these caps. For a homeowner in Hammond or surrounding Lake County, this could mean that while their standard property taxes are capped, the 'voter-approved' or 'stadium-specific' levies could still drive their annual tax bill higher than expected. This distinction is critical for long-term tax planning and real estate investment in the northwest Indiana region.
Furthermore, we must address the concept of economic 'cannibalization' or the substitution effect. When a new entertainment hub is built with public subsidies, it rarely generates entirely 'new' spending in the region. Instead, it often shifts consumer behavior. If a family spends their leisure budget at the stadium, they are often not spending it at local theaters or neighborhood eateries. From a tax perspective, this means local sales tax collections may not see a net increase; the revenue is simply redirected from established local businesses to the new stadium district. This can lead to a 'leakage' effect where the public investment doesn't actually grow the economic pie, but merely reshuffles the slices, potentially leaving some local business owners with lower revenue and higher relative tax burdens.
From a corporate perspective, businesses in Indiana must also consider the role of the Indiana Economic Development Corporation (IEDC). The IEDC frequently utilizes performance-based tax credits, such as the Economic Development for a Growing Economy (EDGE) tax credit. For a project as large as the Chicago Bears' relocation, the scale of these credits could potentially offset hundreds of millions of dollars in corporate tax liability. This creates a secondary tax burden: as a large corporation pays less into the state’s general fund, the state must find other ways to fund statewide services. This often results in a broader tax impact on all residents and smaller businesses that do not qualify for such lucrative incentives, effectively subsidizing the relocation through the collective contributions of the existing tax base.
Finally, there is the issue of government transparency regarding tax abatements. Under the Governmental Accounting Standards Board (GASB) Statement No. 77, local governments are required to disclose the amount of revenue they lose each year due to tax abatement agreements. If Hammond or Arlington Heights enters into a significant agreement with the Bears, these disclosures will become a permanent fixture of their annual financial reports. For businesses looking to relocate to these areas, seeing high levels of tax abatement can be a red flag, signaling that the local tax base is being eroded to support a few large entities. This often leads to future tax hikes on non-subsidized entities to cover the shortfall in public services like road maintenance, police, and fire protection. This level of fiscal complexity is why it is vital for both individuals and businesses to engage with tax professionals who understand the intersection of municipal finance and private development. The potential relocation of the Bears is not just a sports story; it is a case study in how large-scale public subsidies can reshape the financial health of an entire region. By staying informed about legislative changes in both Springfield and Indianapolis, taxpayers can better prepare for the long-term adjustments that will inevitably follow such a massive relocation project. We remain committed to helping our clients navigate these complex tax environments, ensuring that your financial strategy remains robust regardless of where the team ultimately lands.
Want tax & accounting tips and insights?
Sign up for our newsletter.